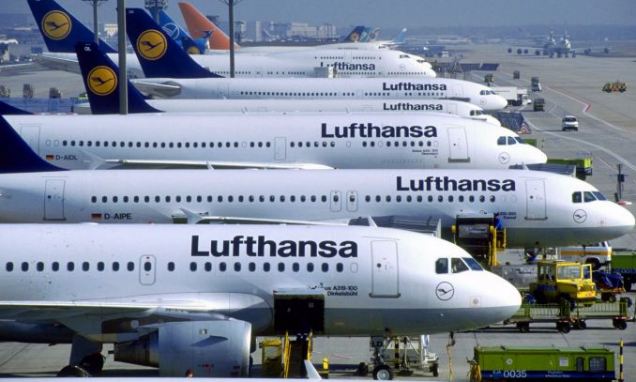
Lufthansa lowered its 2026 profit outlook on Tuesday, November 3, as rising aviation fuel prices threatened to offset stronger-than-expected third-quarter earnings.
The German airline group now anticipates an additional €600 million in fuel expenses this year, prompting management to reduce the upper end of its annual operating profit forecast.
Despite these challenges, Lufthansa reported higher revenue and improved quarterly profitability, supported by strong demand in its cargo and aircraft maintenance businesses.
Lufthansa Cuts 2026 Profit Outlook as Fuel Costs Rise
Lufthansa (ETR: LHAG) revised its full-year adjusted earnings before interest and taxes (EBIT) forecast to between €1.7 billion and €2 billion.
Previously, the company expected adjusted operating profit of €1.7 billion to €2.2 billion.
The downward revision reflects a substantial increase in jet fuel prices, which have climbed amid ongoing geopolitical tensions in the Middle East.
Lufthansa estimates that its total fuel expenses for 2026 will reach approximately €9.3 billion, around €600 million above its previous projection.
Management indicated that achieving the upper end of its earlier earnings forecast is now unlikely.
However, the airline maintained its expectation of higher annual revenue, suggesting that passenger demand remains resilient despite increasing operating costs.
Lufthansa Q3 Earnings Beat Analyst Expectations
Lufthansa delivered stronger-than-expected financial results for the third quarter of 2026.
Adjusted EBIT increased 6% to €1.41 billion, compared with €1.33 billion during the corresponding period last year.
The result exceeded analysts’ average forecast of €1.37 billion, according to estimates compiled by the company.
Quarterly revenue also rose 9% year-over-year to €12.24 billion, surpassing market expectations of €12.08 billion.
Meanwhile, Lufthansa’s net profit climbed 30% to €1.26 billion, compared with €966 million a year earlier.
The results demonstrated the group’s ability to maintain profitability despite higher fuel expenses and operational challenges.
Lufthansa Cargo Profits Surge on Strong Freight Demand
Lufthansa Cargo emerged as one of the group’s strongest-performing divisions during the quarter.
The cargo business reported adjusted EBIT of €162 million, a substantial increase from €49 million in the previous year.
This performance comfortably exceeded analysts’ expectations of €109 million.
Lufthansa attributed the improvement partly to reduced freight capacity among competing airlines in the Middle East.
Higher fuel expenses across the aviation industry also contributed to increased cargo transportation prices.
The combination of stronger pricing and favorable market conditions supported profitability in the division.
Looking ahead, Lufthansa expects fourth-quarter cargo earnings to reach at least the level recorded during the same period in 2025.
Lufthansa Technik Benefits From Higher Maintenance Demand
The group’s aircraft maintenance and repair business also delivered strong financial results.
Lufthansa Technik generated adjusted EBIT of €200 million, compared with €130 million a year earlier.
The figure surpassed the analyst consensus of €165 million, reflecting continued demand for aircraft maintenance, repair, and overhaul services.
Strong demand for these services helped offset weaker performance in parts of Lufthansa’s passenger airline operations.
The division remains an important contributor to the group’s profitability, particularly as airlines continue investing in fleet maintenance and operational reliability.
Network Airlines Earnings Decline Despite Revenue Growth
While Lufthansa’s cargo and maintenance businesses performed strongly, its Network Airlines division faced greater pressure.
The segment, which includes Lufthansa, Swiss International Air Lines, Austrian Airlines, and Brussels Airlines, recorded adjusted EBIT of €853 million.
This represented an 11% decline from €961 million a year earlier and fell below analysts’ expectations of €904 million.
Higher fuel expenses and other operating pressures contributed to the weaker profitability.
Consequently, Lufthansa reduced its full-year adjusted EBIT forecast for Network Airlines to between €600 million and €800 million.
The previous guidance ranged from €750 million to €1.15 billion.
In contrast, the Point-to-Point Airlines division, which includes Eurowings, delivered improved results.
Adjusted EBIT increased to €214 million from €197 million a year earlier, exceeding the €192 million analyst estimate.
Lufthansa maintained its full-year earnings outlook for this business.
Higher Fuel Costs and Labor Disputes Weigh on Nine-Month Results
Despite the stronger third-quarter performance, Lufthansa’s profitability remained under pressure during the first nine months of 2026.
Adjusted EBIT declined 20% to €1.18 billion, compared with €1.48 billion during the same period in 2025.
The decline reflected several challenges, including higher aviation fuel prices, disruptions associated with the Middle East conflict, and labor disputes involving pilots and cabin crew.
Nevertheless, the company’s fuel hedging strategy provided substantial financial protection.
Lufthansa recorded a €1.21 billion gain from fuel hedging, compared with a €204 million loss a year earlier.
These hedging arrangements helped reduce the impact of volatile energy prices on the group’s financial performance.
However, prolonged increases in fuel costs could continue to affect profitability as existing hedging contracts expire.
Lufthansa Reduces Capital Spending as Aircraft Deliveries Slow
Lufthansa also revised its investment plans for the remainder of 2026.
The airline lowered its full-year net capital expenditure forecast to approximately €2.1 billion, compared with its previous estimate of €2.5 billion.
The reduction primarily reflects fewer aircraft deliveries than originally scheduled.
Although lower capital spending may provide short-term financial flexibility, delayed deliveries could affect the group’s fleet modernization plans.
Aircraft availability remains an important consideration for Lufthansa as it seeks to improve efficiency, control operating expenses, and maintain competitive services.
Lufthansa Moves Forward With TAP Air Portugal Investment
Separately, Lufthansa continues pursuing its proposed investment in Portuguese national airline TAP Air Portugal.
On October 14, Portugal’s government selected Lufthansa’s offer of approximately €1.03 billion for a 44.9% ownership stake in TAP.
The transaction forms part of the Portuguese government’s broader airline privatization strategy.
The proposed investment would strengthen Lufthansa’s international network and expand its presence in important markets, including routes connecting Europe with Latin America.
However, the acquisition remains subject to regulatory approval and completion of the required transaction procedures.
If finalized, the agreement could provide Lufthansa with additional long-term growth opportunities.
Lufthansa Outlook Remains Cautious Despite Strong Q3 Results
Lufthansa’s third-quarter earnings highlight the contrasting forces shaping the airline industry’s financial outlook.
Strong passenger demand, improved cargo profitability, and higher maintenance earnings supported the company’s quarterly performance.
However, rising fuel prices, operational disruptions, and weaker profitability at its network airlines continue to present significant challenges.
Management expects full-year results to depend on travel demand, energy costs, and the performance of Lufthansa Cargo during the final quarter.
Investors will also monitor developments in the Middle East, aircraft delivery schedules, and the airline’s efforts to control expenses.
For now, Lufthansa’s reduced 2026 profit outlook demonstrates how rising fuel costs can pressure earnings even when revenue and operating performance exceed expectations.