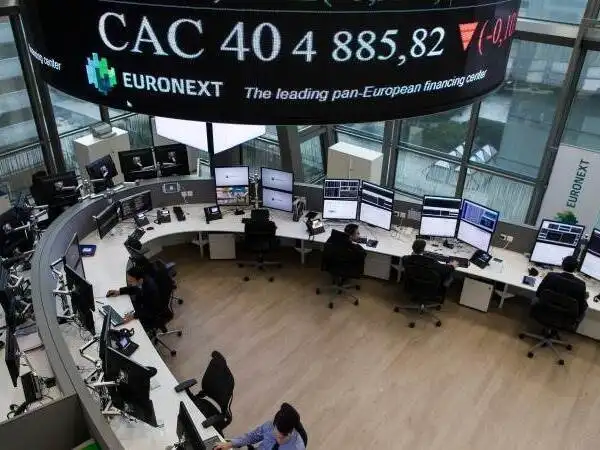
European stocks moved higher on Wednesday, approaching one-week highs as investors prepared for a busy schedule of economic data from Europe and the United States.
Positive developments surrounding the technology and artificial intelligence sectors also helped improve market sentiment. The pan-European STOXX 600 gained around 0.7%, while Germany’s DAX and the UK’s FTSE 100 also advanced roughly 0.7%.
European Tech Stocks Gain on AI Optimism
Technology and semiconductor-related shares were among the strongest contributors to the European market rebound.
The gains followed developments in Washington, where U.S. President Donald Trump and executives from major technology companies announced voluntary safety standards covering advanced artificial intelligence systems.
The agreement focuses on internal controls, independent reviews and greater oversight of AI development.
Trump also reiterated support for expanding U.S. data-center infrastructure, an important factor for semiconductor manufacturers, power providers and other companies exposed to the rapid growth of AI.
The comments helped ease some investor concerns about potential restrictions on AI infrastructure investment.
European Economic Data Takes Center Stage
Investors are also preparing for several important economic releases across Europe.
German retail sales and employment figures are among the key indicators in focus, along with preliminary inflation data from France and Germany’s September CPI report.
These figures could provide fresh clues about inflation, economic growth and the future direction of European monetary policy.
U.S. PCE Inflation in Focus
Across the Atlantic, attention is centered on the U.S. Personal Consumption Expenditures price index for August.
The PCE index is the Federal Reserve’s preferred measure of inflation and could have a significant impact on expectations for U.S. interest rates.
Markets will be watching closely to see whether underlying inflation pressures remain stable.
A softer or unchanged reading could provide some relief to equity markets, particularly rate-sensitive sectors such as technology.
Treasury Yields Remain a Key Risk
High U.S. Treasury yields continue to represent a major challenge for global equities.
Bond yields have recently traded close to multi-decade highs, increasing borrowing costs and putting pressure on stock valuations.
Any sign that inflation is easing could therefore support expectations that the Federal Reserve may not need to tighten monetary policy more aggressively than markets currently anticipate.
ECB Comments Also in Focus
European investors are also awaiting comments from European Central Bank official Frank Elderson.
Markets will look for any new signals regarding inflation, economic growth and the broader monetary policy outlook for the eurozone.
STOXX 600 Heads for September Loss
Despite Wednesday’s rebound, European stocks have endured a difficult September.
The STOXX 600 is on track to fall nearly 2% for the month, which would end a five-month streak of monthly gains.
The decline marks a reversal from the stronger performance seen during the summer.
Rising government bond yields, elevated energy costs and uncertainty surrounding the pace of AI-sector investment have all weighed on European equity valuations.
Nevertheless, Wednesday’s recovery shows that technology and AI-related developments remain important drivers of market sentiment as investors prepare for the next round of inflation and economic data.