The U.S. dollar steadied on Friday as its recent rally lost momentum ahead of key labor-market data due later in the day.
Meanwhile, the Japanese yen strengthened after Tokyo inflation came in hotter than expected, increasing expectations that the Bank of Japan could raise interest rates again.
Broader currency markets were relatively quiet as investors also reacted to a sharp selloff in global bonds and rising oil prices.
Dollar Rally Pauses Before Nonfarm Payrolls
The U.S. dollar index and dollar index futures both slipped by nearly 0.2%.
Despite the pullback, the dollar remained on track for a weekly gain of about 1%, which would mark its third consecutive week of advances.
Investor attention is now firmly focused on the September U.S. nonfarm payrolls report.
The data could provide fresh clues about the strength of the U.S. economy and the outlook for Federal Reserve interest-rate policy.
Strong U.S. Economy Supports the Dollar
The dollar has recently benefited from signs that the U.S. economy remains resilient.
Continued economic strength could give the Federal Reserve more room to maintain higher interest rates or raise them further if inflation remains elevated.
Several Fed officials reinforced that message overnight.
Minneapolis Fed President Neel Kashkari and Dallas Fed President Lorie Logan both indicated that additional rate increases may be needed to bring persistent inflation under control.
Fed Governor Lisa Cook also highlighted potential inflation risks linked to artificial intelligence, particularly as rapid AI investment adds pressure to global supply chains.
Labor Market Data Could Shape Fed Policy
Any signs of continued strength in the U.S. labor market could strengthen expectations for additional monetary tightening.
The Federal Reserve remains focused on bringing inflation back toward its 2% annual target.
Recent PCE price index data for August showed some moderation in price pressures. However, core inflation remained above the Fed’s target.
As a result, Friday’s payrolls report could play an important role in shaping market expectations for the next steps in U.S. monetary policy.
Yen Strengthens After Hot Tokyo Inflation
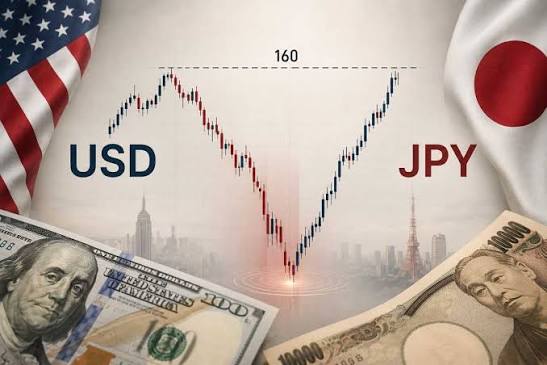
The Japanese yen gained against the dollar, with USD/JPY falling by nearly 0.2%.
The move followed stronger-than-expected inflation data from Tokyo.
Both headline and core consumer price inflation rose to their highest levels since November 2025, while underlying inflation remained comfortably above the Bank of Japan’s 2% target.
The stronger inflation figures increased expectations that the BOJ could raise interest rates again in the coming months.
BOJ Rate Hike Expectations Rise
The Bank of Japan raised interest rates by 25 basis points in September and signaled that further hikes remain possible.
Expectations for additional tightening also supported demand for Japanese government bonds.
The benchmark 10-year Japanese government bond yield fell around 1.25% after reaching a 30-year high earlier in the week.
Euro and Pound Trade Quietly
Elsewhere in currency markets, the euro and British pound both posted modest gains of less than 0.1%.
Trading remained subdued as investors waited for the U.S. payrolls release and continued to monitor developments in global bond and energy markets.
The Australian dollar was broadly unchanged, while the Singapore dollar also traded close to flat.
South Korean Won Holds Steady
The South Korean won remained relatively stable after consumer inflation came in slightly below expectations.
September inflation eased modestly but remained above the Bank of Korea’s target.
USD/KRW declined slightly as traders assessed the implications for future South Korean monetary policy.
Indian Rupee Falls Toward Record Lows
The Indian rupee was among the weakest major Asian currencies.
USD/INR rose around 0.4%, bringing the pair back toward record highs reached earlier in the year.
Higher oil prices remain a major source of pressure for the rupee because India relies heavily on imported energy.
Rising crude costs can increase the country’s import bill and place additional pressure on the currency.
Chinese Yuan Edges Higher
The offshore Chinese yuan also strengthened slightly, with USD/CNH falling around 0.1%.
Trading activity remained limited, however, as Chinese financial markets are scheduled to stay closed until the following Thursday.
Currency Markets Await the Next Catalyst
The main focus for traders now remains the U.S. nonfarm payrolls report.
A stronger-than-expected jobs reading could reinforce expectations for higher U.S. interest rates and provide renewed support for the dollar.
At the same time, hotter inflation in Japan has strengthened expectations for further Bank of Japan tightening, providing support for the yen.